
Ahold Delhaize reports resilient Q3 2026 results and updates 2026 guidance to reflect business disruption caused by recent cybersecurity incident
- Through our family of great local brands, we remain closely connected to the needs of customers and communities. Disciplined investments in value, quality and convenience are strengthening our competitive positions and enabling us to continue to gain market share. This balanced approach supports sustainable, long-term growth and positions us to deliver on our Growing Together strategic ambitions.
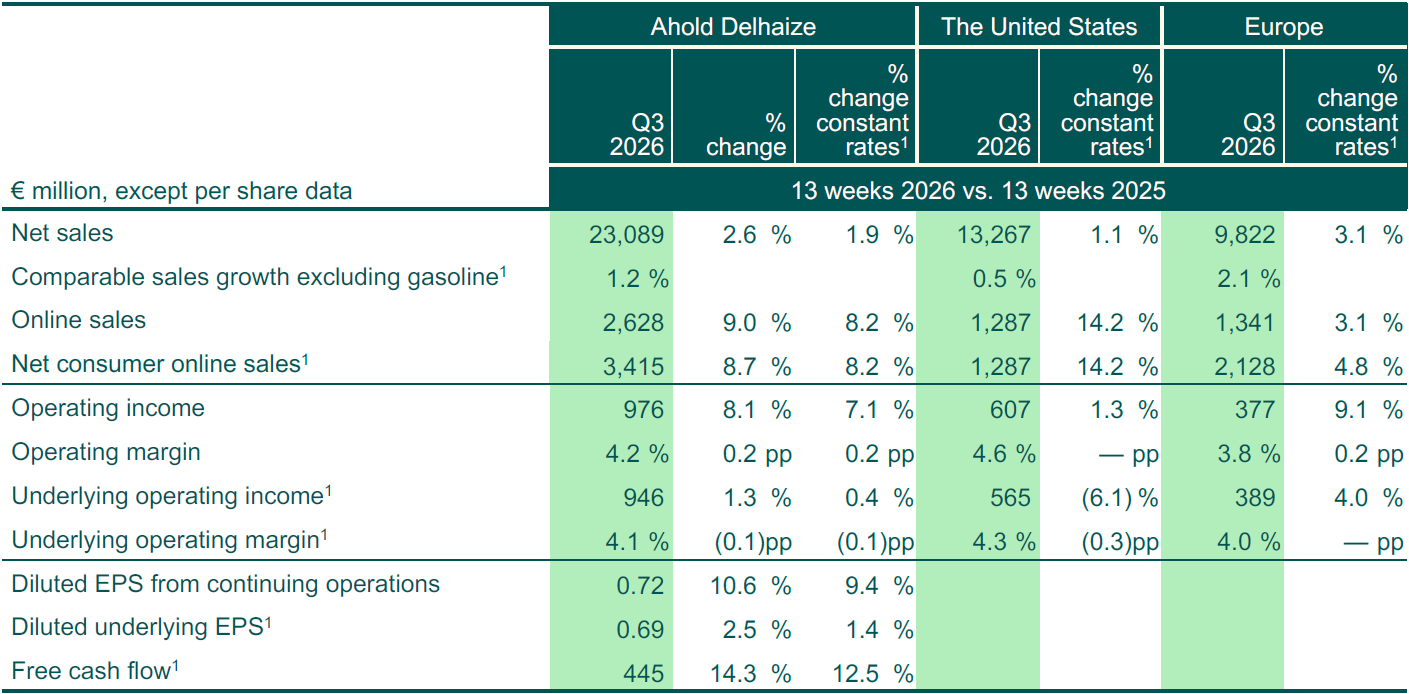
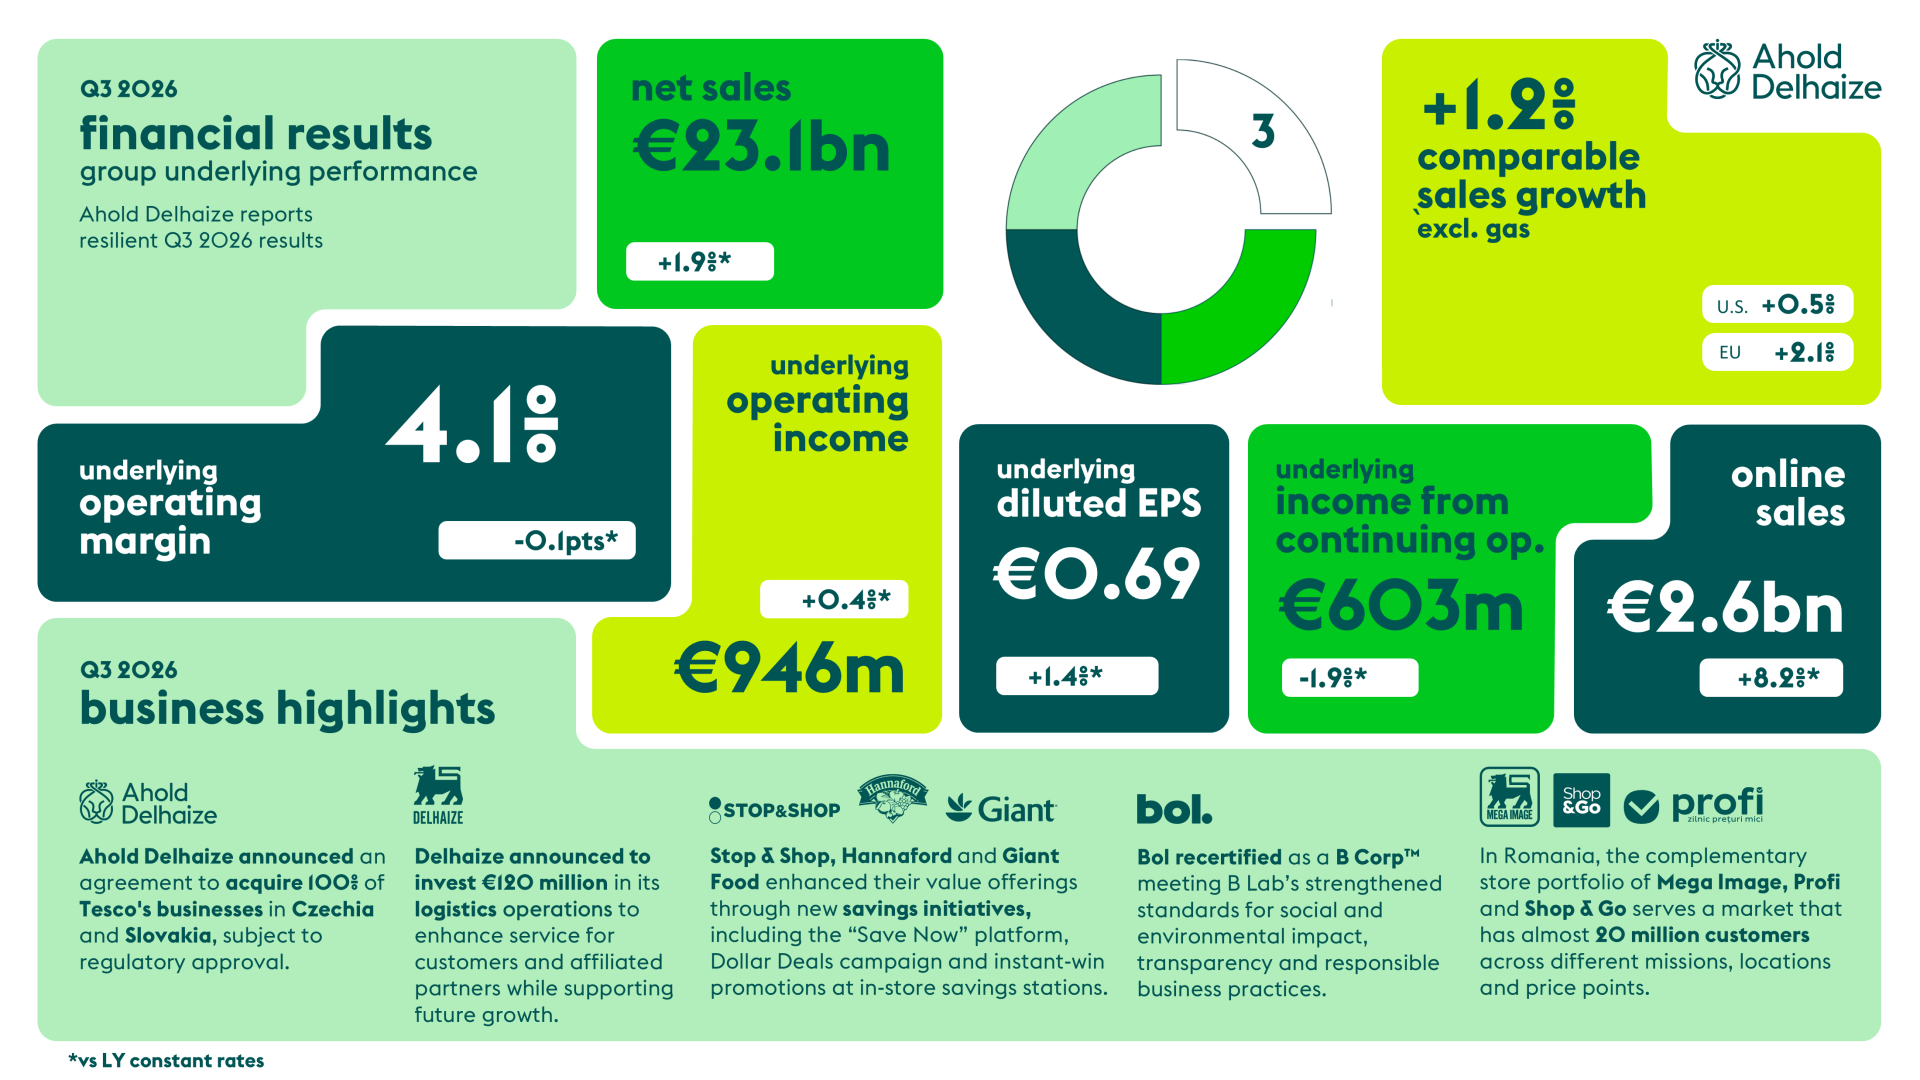
- Q3 net sales were €23.1 billion, up 1.9% at constant exchange rates and up 2.6% at actual exchange rates.
- Q3 comparable sales excluding gasoline increased 0.5% in the U.S. Several market-specific factors, including reduced SNAP benefits, the cyclospora outbreak and egg price deflation, alongside pharmacy pricing changes related to the Inflation Reduction Act, reduced our growth rate by approximately 2.1 percentage points. This was partially offset by 0.2 percentage points due to weather.
- Q3 comparable sales excluding gasoline increased 2.1% in Europe. Accelerating volumes amid deflation in most of our European markets highlight the appeal of our brands’ value propositions and convenient shopping solutions.
- Ahold Delhaize's online sales increased 8.2% in Q3 at constant exchange rates and 9.0% at actual exchange rates. This was driven by strong growth of 14.2% at constant exchange rates in the U.S., where customers continue to appreciate the convenience, assortments and personalization offered by our brands' online shopping experiences, supported by our strong omnichannel model.
- Q3 underlying operating margin was 4.1%, a decrease of 0.1 percentage points at constant exchange rates. A favorable discounting effect on insurance provisions at Ahold Delhaize Group, driven by interest rate developments, was offset by a modest decline in the U.S., in part from cycling prior-year nonrecurring items.
- Q3 diluted underlying earnings per share (EPS) was €0.69, an increase of 1.4% compared to the prior year at constant exchange rates.
- Q3 IFRS operating income was €976 million and IFRS-diluted EPS from continuing operations was €0.72. IFRS results were €30 million higher than underlying results, primarily due to a pension settlement in the U.S.
- Q3 free cash flow was €445 million, driven by improvements in working capital, partially offset by higher purchases of non-current assets and new supplier payment regulations in Serbia.
- In October, a cybersecurity incident affected our business and, based on current estimations, is expected to reduce Q4 net sales by between €200 million and €250 million and underlying and IFRS operating income by between €75 million and €100 million. In addition, we expect incremental response and remediation costs to have a marginal impact on 2026 IFRS operating income (see Note 13: Subsequent events in the full interim report).
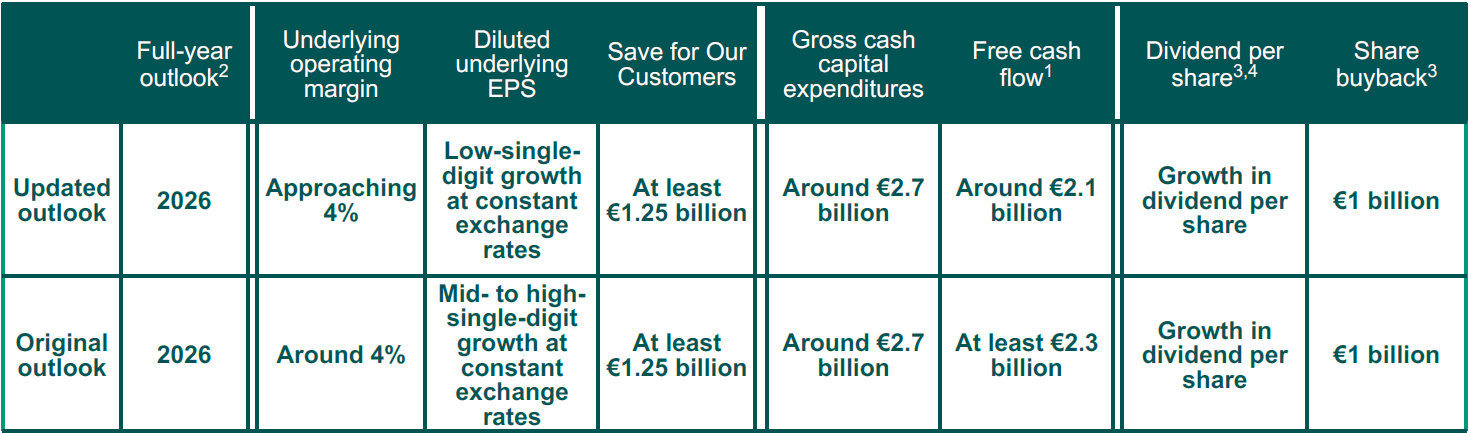
- For 2026, the Company now expects (on a 53-week basis): underlying operating margin approaching 4.0% (previously around 4.0%); low-single-digit diluted underlying EPS growth at constant exchange rates (previously mid- to high-single-digit); and free cash flow of around €2.1 billion (previously at least €2.3 billion).
- Ahold Delhaize announces a €1 billion share buyback program to start at the beginning of 2027 and we aim to grow our dividend per share for 2026 at a mid-single-digit rate this year, based on this outlook.
Zaandam, the Netherlands, November 4, 2026 – Ahold Delhaize, an international food retail group and a leader in both supermarkets and e-commerce, reports third quarter results today.
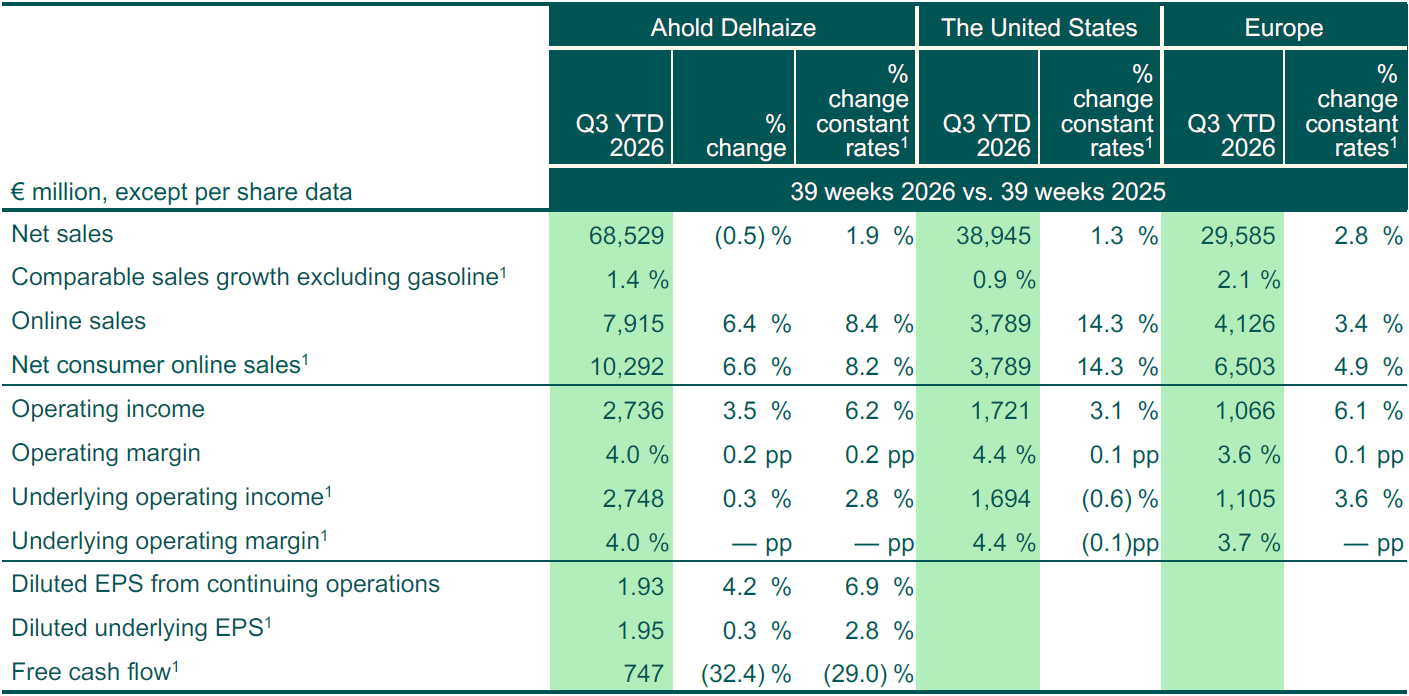
Summary of key financial data
1. Comparable sales growth excluding gasoline, net consumer online sales, underlying operating income and related margin, diluted underlying EPS, free cash flow, and percentage change at constant rates are alternative performance measures that are used throughout this report. For a description of alternative performance measures and a reconciliation between percentage change and percentage change at constant rates, see Note 12 in the full interim report.
1. Comparable sales growth excluding gasoline, net consumer online sales, underlying operating income and related margin, diluted underlying EPS, free cash flow, and percentage change at constant rates are alternative performance measures that are used throughout this report. For a description of alternative performance measures and a reconciliation between percentage change and percentage change at constant rates, see Note 12 in the full interim report.
Comments from Frans Muller, President and CEO of Ahold Delhaize
“Our resilient third-quarter performance reflects the progress we are making on the execution of our Growing Together strategy. As households remain focused on value, our brands’ deep understanding of customers enables them to respond with the right combination of affordability, quality, healthy choices and convenience. By listening closely and investing consistently in compelling customer value propositions, we strengthen customer loyalty, supporting positive volume growth in both regions and market share gains across our key markets.
“Q3 net sales grew 1.9% at constant rates (increased 2.6% at actual rates), with comparable sales growth excluding gasoline of 1.2%. Strong cost discipline and steady execution of our Save for Our Customers program supported a healthy underlying operating margin of 4.1%, enabling us to absorb cost pressures from, among others, higher gasoline prices while continuing to invest in customer value. On an IFRS basis, we delivered operating income of €976 million. This was higher than underlying operating income, primarily due to a pension settlement related gain in our U.S. business.
“In the U.S., net sales increased 1.1% at constant rates (increased 2.6% at actual rates) and comparable sales excluding gasoline grew 0.5%. Importantly, we delivered positive volume growth, reflecting the strength of our brands. Top line growth continued to be influenced by several market-specific factors, including reduced SNAP benefits, the cyclospora outbreak and egg price deflation, alongside pharmacy pricing changes related to the Inflation Reduction Act. Together, these reduced our growth rate by approximately 2.1 percentage points.
“Our U.S. brands remain focused on investing in price, expanding own-brand assortments and extending their reach to serve more customers. For example, Hannaford’s renewed focus on everyday low prices and simplified value messaging under a single ‘Save Now’ platform has improved price perception and supported positive volume growth. These efforts are complemented by our omnichannel capabilities, which give customers the convenience to shop with our brands whenever, wherever and however they choose. Online sales grew 14.2%, marking the tenth consecutive quarter of double-digit growth, and online retention continues to strengthen, reaching over 75% quarter-on-quarter. At the same time, we continue to invest in expanding our physical footprint and enhancing the customer experience. Food Lion recently opened one new store and launched omnichannel remodels at 92 stores in its Greensboro, North Carolina, market and preparations are already underway for the next round of remodels in the Richmond and Raonoke markets. This provides a strong runway into 2027, as the brand prepares to further accelerate growth.
“In Europe, net sales increased 3.1% at constant rates (increased 2.7% at actual rates) and comparable sales excluding gasoline grew 2.1%. Positive comparable sales growth and accelerating volumes amid deflation in most of our markets highlight the appeal of our brands’ value propositions and convenient shopping solutions. Delhaize continued to perform exceptionally well in Belgium, supported by compelling summer campaigns, strong seasonal assortments and a customer-focused offering that resonated throughout the quarter. In Romania, our complementary portfolio of Mega Image, Profi and Shop & Go positions us well to serve customers across different missions, locations and price points, creating a platform to unlock future growth opportunities. And in Serbia, Maxi is winning back market share through compelling own-brand offerings, attractive promotions and an extensive range of price favorites.
“Since the end of the quarter, in October, our business was impacted by a cybersecurity incident. As part of our protocols to assess and mitigate cybersecurity incidents, we took some systems offline to help protect our IT environment. To differing degrees, this mainly affected our online capabilities in the Benelux and the U.S., as well as our Benelux supply-chain operations. Bol was not impacted. This, unfortunately, meant that we were not always able to deliver the level of service our customers can expect from us. We apologize to our brands' customers for the disruption and inconvenience this caused and are deeply grateful for their trust, loyalty and understanding. As our brands welcome them back, we are showing our appreciation through special promotions and other small gestures.
“I also want to sincerely thank our colleagues, who worked day and night to get our operations back on track to serve customers. They did this in close, and highly appreciated, cooperation with our partners, authorities and peers. While most of the disruption was contained within two weeks, work continues to fully restore our normal operations. As we all recognize, cyber threats are an increasingly harsh reality of doing business today, and moments like these remind us not only of our shared vulnerabilities, but also of the strength of our relationships and the importance of standing together.
“While the cybersecurity incident has, understandably, demanded significant attention, it is important that we keep it in perspective. Our response demonstrates the resilience of our business; the incident does not define our business. Our strategic priorities remain unchanged, and our focus continues to be on executing our strategy, serving our customers and creating sustainable long-term value. Our resilience enables us to navigate disruption; our strategy ensures we continue to move forward.
“Across our business, technology, data and AI are becoming increasingly powerful drivers of productivity, generating savings that we can reinvest in value, service and innovation for our brands' customers. A great example of this is everything we do in mechanization. At Albert Heijn, automated Home Shop Centers have improved productivity by more than 20%, while initiatives at Albert Heijn and bol have increased output capacity by 10%. And what excites me is that we are moving beyond individual success stories. We are scaling what works and bringing proven technologies to more parts of our business. That includes the new Food Lion distribution center in North Carolina and the supply chain projects we are continuing to advance across Europe, creating capacity for future growth, improving efficiency and, in the end, delivering an even better shopping experience for our customers.
“Ultimately, that is what these investments are all about: using the scale and capabilities of our business to make everyday life better for our our brands' customers. That goes beyond convenience and value. It is also about helping them make healthier choices. Helping people live healthier lives is a clear opportunity: our latest research among more than 8,000 consumers found that 92% want to eat healthier, yet only 14% believe their diets are very healthy. Our brands are helping bridge that gap in practical and engaging ways. Albert Heijn’s Hamster Chefs product range and Disney Diskeyz campaign inspire families and children to eat more fruits and vegetables. Delhaize is investing in freshness, innovation, convenience and affordability. The GIANT Company offers personalized nutrition guidance, pharmacy expertise and wellness resources for shoppers using GLP-1 medications, helping them on their personal health journeys. Together, these initiatives bring our healthy communities ambition to life, helping customers make choices that work for their needs, lifestyles and budgets, while strengthening the trust and loyalty that underpin long-term growth.
“While the majority of value creation in our Growing Together strategy is driven by organic growth opportunities, we are also actively looking to scale our portfolio through acquisitions. Here we follow a disciplined approach and are particularly focused on in-market and adjacent market opportunities, where we already have strong operational presence and brand recognition. We are pleased to announce our agreement to acquire 100% of Tesco Czechia and Slovakia, subject to the satisfaction of customary closing conditions, including regulatory clearances. Following completion, integration and store portfolio remodeling for long-term success, the combined businesses of our local brand Albert and Tesco Czechia are expected to become the leading grocery retail brand in Czechia by market share and Ahold Delhaize will be established as a significant player in Slovakia, with a leading brand position. This is an excellent example of our Growing Together strategy in action, bringing our local food retail expertise together with a clear capital allocation policy to deliver long-term shareholder returns through multiple levers.
“With the year drawing to a close, I am proud of the resilience our brands and teams have demonstrated in navigating dynamic market conditions while continuing to serve customers and advance our strategic priorities. As we look ahead, we remain focused on sustaining momentum, strengthening local execution and accelerating progress across our markets. Our brands are gearing up for the holiday season with compelling promotions and inspiring seasonal assortments, helping customers make the most of the moments that matter with friends and family. As the cybersecurity incident has had an adverse impact on our fourth-quarter performance, we are also updating our outlook for the year.
“Based on current estimations, we expect that the incident will reduce net sales by between €200 million and €250 million and underlying and IFRS operating income by between €75 million and €100 million. In addition, we expect incremental response and remediation costs to have a marginal impact on 2026 IFRS operating income. Reflecting these effects, we have updated our full-year outlook. We now anticipate underlying operating margin to approach 4.0% (previously around 4.0%) and diluted underlying EPS growth at constant exchange rates to be in the low-single-digits (previously mid- to high-single-digits). Taking into account the impact of the cybersecurity incident and new supplier payment regulations in Serbia, we now expect free cash flow of around €2.1 billion (previously at least €2.3 billion).
“Our commitment to the broader Growing Together targets remains unchanged. Our confidence in the longterm strength of the business is reflected in the continuation of our €1 billion annual share buyback program in 2027 and our expectations to grow our dividend per share for 2026 at a mid-single-digit rate this year.”
Q3 Financial highlights
Group highlights
Ahold Delhaize's net sales were €23.1 billion, an increase of 1.9% at constant exchange rates and up 2.6% at actual exchange rates. Our net sales growth was driven by comparable sales growth excluding gasoline of 1.2%, higher gasoline sales, the Delfood acquisition and net store openings. The Company's Q3 comparable sales excluding gasoline were positively impacted by 0.2 percentage points due to weather and calendar shifts and negatively by 0.4 percentage points due to a reduction in pharmacy prices related to the Inflation Reduction Act. Egg price deflation, a cyclospora produce outbreak, and lower SNAP benefits from program changes in the U.S. had a negative impact of 0.9 percentage points.
In Q3, Ahold Delhaize's online sales increased 8.2% at constant exchange rates. This was driven by 14.2% growth in the U.S.
Ahold Delhaize's underlying operating margin was 4.1%, a decrease of 0.1 percentage points at constant exchange rates. A favorable discounting effect on insurance provisions at Ahold Delhaize Group, driven by interest rate development, was offset by a modest decline in the U.S., in part, from cycling prior-year nonrecurring items.
Ahold Delhaize's IFRS operating income was €976 million, representing an IFRS operating margin of 4.2%. IFRS results were €30 million higher than underlying results, primarily due to a pension settlement in the U.S.
Diluted EPS from continuing operations was €0.72 and diluted underlying EPS was €0.69, up 1.4% at constant exchange rates compared to last year's results.
In the quarter, Ahold Delhaize purchased 8.6 million of its own shares for €280 million, bringing the total amount to €844 million in the first three quarters of the year.
U.S. highlights
U.S. net sales were €13.3 billion, an increase of 1.1% at constant exchange rates and up 2.6% at actual exchange rates. Net sales growth was driven by 0.5% comparable sales growth excluding gasoline and higher gasoline sales. Comparable sales growth excluding gasoline was driven by continued growth in online sales. Weather had a positive impact of 0.2 percentage points and pharmacy prices related to the Inflation Reduction Act had a negative impact of 0.6 percentage points. Egg deflation, a cyclospora produce outbreak, and lower SNAP benefits from program changes had a negative impact of 1.5 percentage points.
In Q3, online sales increased 14.2% at constant exchange rates, marking the tenth consecutive quarter of double-digit growth. Food Lion led brand performance with over 20% growth.
Underlying operating margin in the U.S. was 4.3%, down 0.3 percentage points as a result of the cycling of prior-year non-recurring items, price investments, higher utility costs, and the absorption of indirect costs from higher energy prices, partially offset by a favorable mix in pharmacy.
The U.S. Q3 IFRS operating income was €607 million, representing an IFRS operating margin of 4.6%. IFRS results were higher than underlying results, primarily due to a pension settlement.
Europe highlights
European net sales were €9.8 billion, an increase of 3.1% at constant exchange rates and 2.7% at actual exchange rates. Higher net sales were due to comparable sales growth excluding gasoline of 2.1%, the Delfood acquisition and net store openings. Calendar shifts had a positive impact of 0.1 percentage points.
In Q3, online sales increased 3.1%, keeping pace with the prior quarter as we maintained our strong market positions in a competitive and challenging consumer environment. Performance at bol was negatively impacted by an incident impacting the supply chain at one of their warehousing partners and ongoing consumer pressures contributing to downtrading within bol's assortment.
Underlying operating margin in Europe was 4.0%, in line with prior year. Lower turnover tax rate (IMCA) and the realization of synergies in Romania were offset by lower performance in Serbia following last year's governmental decree on grocery industry pricing and the absorption of indirect costs from higher energy prices.
Europe's Q3 IFRS operating income was €377 million, representing an IFRS operating margin of 3.8%.
Outlook
As a result of the cybersecurity incident, we expect, based on current estimations, an adverse impact on our fourth-quarter performance, reducing net sales by between €200 million and €250 million and underlying and IFRS operating income by between €75 million and €100 million. In addition, incremental response and remediation costs are expected to have a marginal impact on 2026 IFRS operating income. Reflecting these effects, we have updated our full-year outlook. We now anticipate underlying operating margin to approach 4.0% (previously around 4.0%) and diluted underlying EPS growth at constant exchange rates to be in the low-single-digits (previously mid- to high-single-digits). Taking into account the impact of the cybersecurity incident and new payment regulations in Serbia, we now expect free cash flow of around €2.1 billion (previously at least €2.3 billion).
The following are other changes in the business that impact comparable performance for 2026 and that have been incorporated into our Outlook:
- The Inflation Reduction Act is impacting U.S. pharmacy sales. It is expected to have an approximate $450 million negative impact on reported and comparable store sales in the U.S.
There is no material impact on underlying operating income. - The acquisition of Delfood closed on February 2, 2026, and is expected to add around €200 million in net sales to our Europe segment.
- There will be a 53rd week in 2026, which is expected to have a positive impact of 1.5-2% on net sales and a positive impact of around 2-3% on underlying income from continuing operations. This does not significantly impact underlying operating margin.
1. Excludes M&A.
2. 2026 is a 53-week calendar year.
3. Management remains committed to the Company's share buyback and dividend programs while continuously assessing macroeconomic, geopolitical and legislative factors as part of its decision-making process. In addition, the programs may be adjusted in response to corporate activities, including significant mergers and acquisitions.
4. Our dividend policy is to target a dividend payout ratio range of 40-50%.
downloads
webcast
This communication contains information that qualifies as inside information within the meaning of Article 7(1) of the EU Market Abuse Regulation.
This communication includes forward-looking statements. All statements other than statements of historical facts may be forward-looking statements. Forward-looking statements can be identified by certain words, such as “anticipate,” “intend,” “plan,” “goal,” “seek,” “believe,” “project,” “estimate,” “expect,” “strategy,” “future,” “likely,” “may,” “should,” “will” and similar references to future periods.
Forward-looking statements are subject to risks, uncertainties and other factors that are difficult to predict and that may cause the actual results of Koninklijke Ahold Delhaize N.V. (the “Company”) to differ materially from future results expressed or implied by such forward-looking statements. Therefore, you should not place undue reliance on any of these forward-looking statements. Factors that might cause or contribute to such a material difference include, but are not limited to, risks relating to the Company’s inability to successfully implement its strategy, manage the growth of its business or realize the anticipated benefits of acquisitions; risks relating to competition and pressure on profit margins in the food retail industry; the impact of economic conditions, including high levels of inflation, on consumer spending; changes in consumer expectations and preferences; turbulence in the global capital markets; political developments, natural disasters and pandemics; wars and geopolitical conflicts; climate change; energy supply issues; raw material scarcity and human rights developments in the supply chain; disruption of operations and other factors negatively affecting the Company’s suppliers; the unsuccessful operation of the Company’s franchised and affiliated stores; changes in supplier terms and the inability to pass on cost increases to prices; risks related to environmental, social and governance matters (including performance) and sustainable retailing; risks related to data management and data privacy; food safety issues resulting in product liability claims and adverse publicity; environmental liabilities associated with the properties that the Company owns or leases; competitive labor markets, changes in labor conditions and labor disruptions; increases in costs associated with the Company’s defined benefit pension plans; ransomware and other cybersecurity issues relating to the failure or breach of security of IT systems; disruption from developments in artificial intelligence or inability to realize related benefits; the impact of adverse publicity or operational disruption related to activism or negative media coverage; the Company’s inability to successfully complete divestitures and the effect of contingent liabilities arising from completed divestitures; antitrust and similar legislation; unexpected outcomes in the Company’s legal proceedings; additional expenses or capital expenditures associated with compliance with federal, regional, state and local laws and regulations; unexpected outcomes with respect to tax audits; the impact of the Company’s outstanding financial debt; the Company’s ability to generate positive cash flows; fluctuation in interest rates; the change in reference interest rate; the impact of downgrades of the Company’s credit ratings and the associated increase in the Company’s cost of borrowing; exchange rate fluctuations; inherent limitations in the Company’s control systems; changes in accounting standards; inability to obtain effective levels of insurance coverage; adverse results arising from the Company’s claims against its self-insurance program; the Company’s inability to locate appropriate real estate or enter into real estate leases on commercially acceptable terms; and other factors discussed in the Company’s public filings and other disclosures.
Forward-looking statements reflect the current views of the Company’s management and assumptions based on information currently available to the Company’s management. Forward-looking statements speak only as of the date they are made, and the Company does not assume any obligation to update such statements, except as required by law.