
Ahold Delhaize reports strong Q3 performance; 2025 outlook reconfirmed

- Through our family of great local brands, we have a strong understanding of what matters most to our customers. By making investments in pricing, expanding own-brand assortments and enhancing personalized loyalty programs, we deliver great value and trusted quality. Our focus on healthy and convenient options is especially important amid continued pressure on household budgets. Playing our role in local communities is deeply engrained in our culture and our brands' equity, and is an important differentiator in driving sustainable, long-term omnichannel growth.
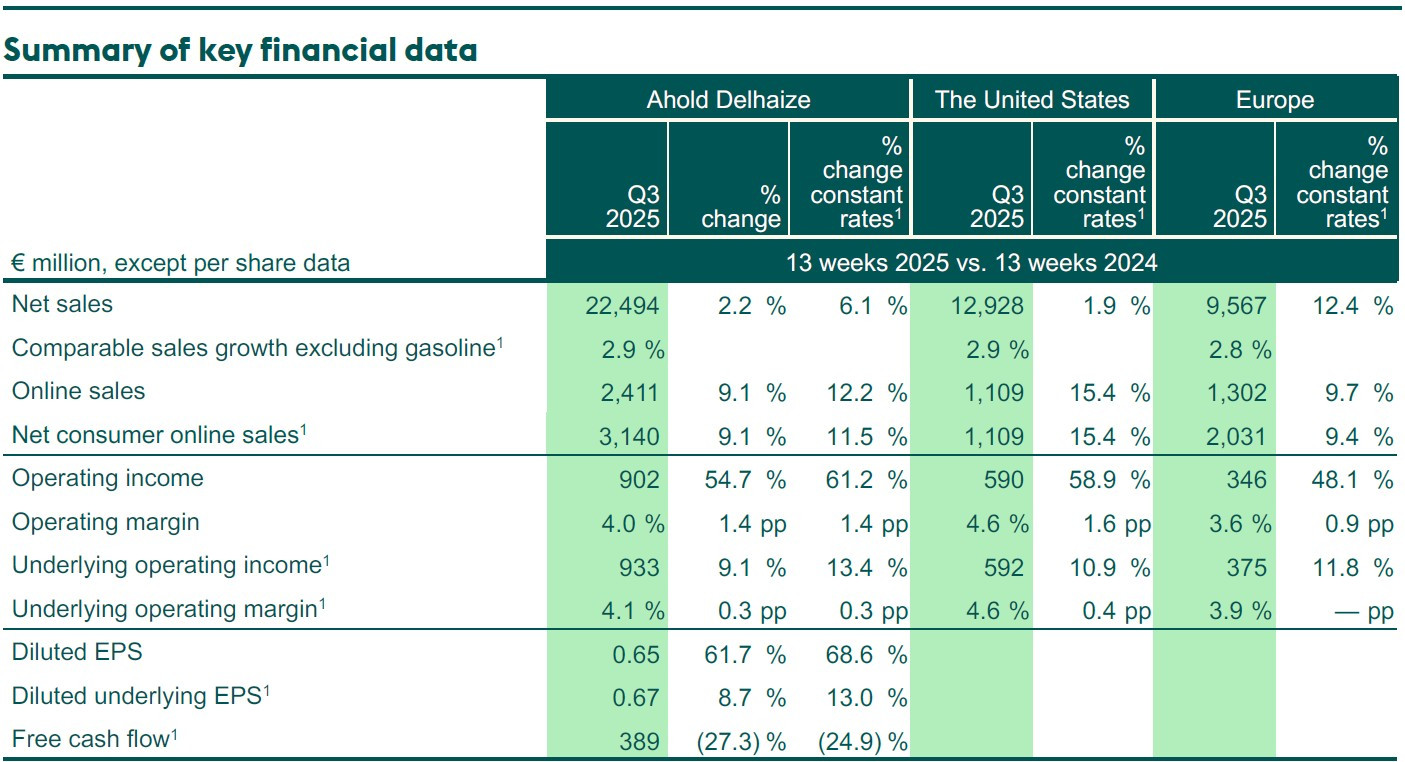
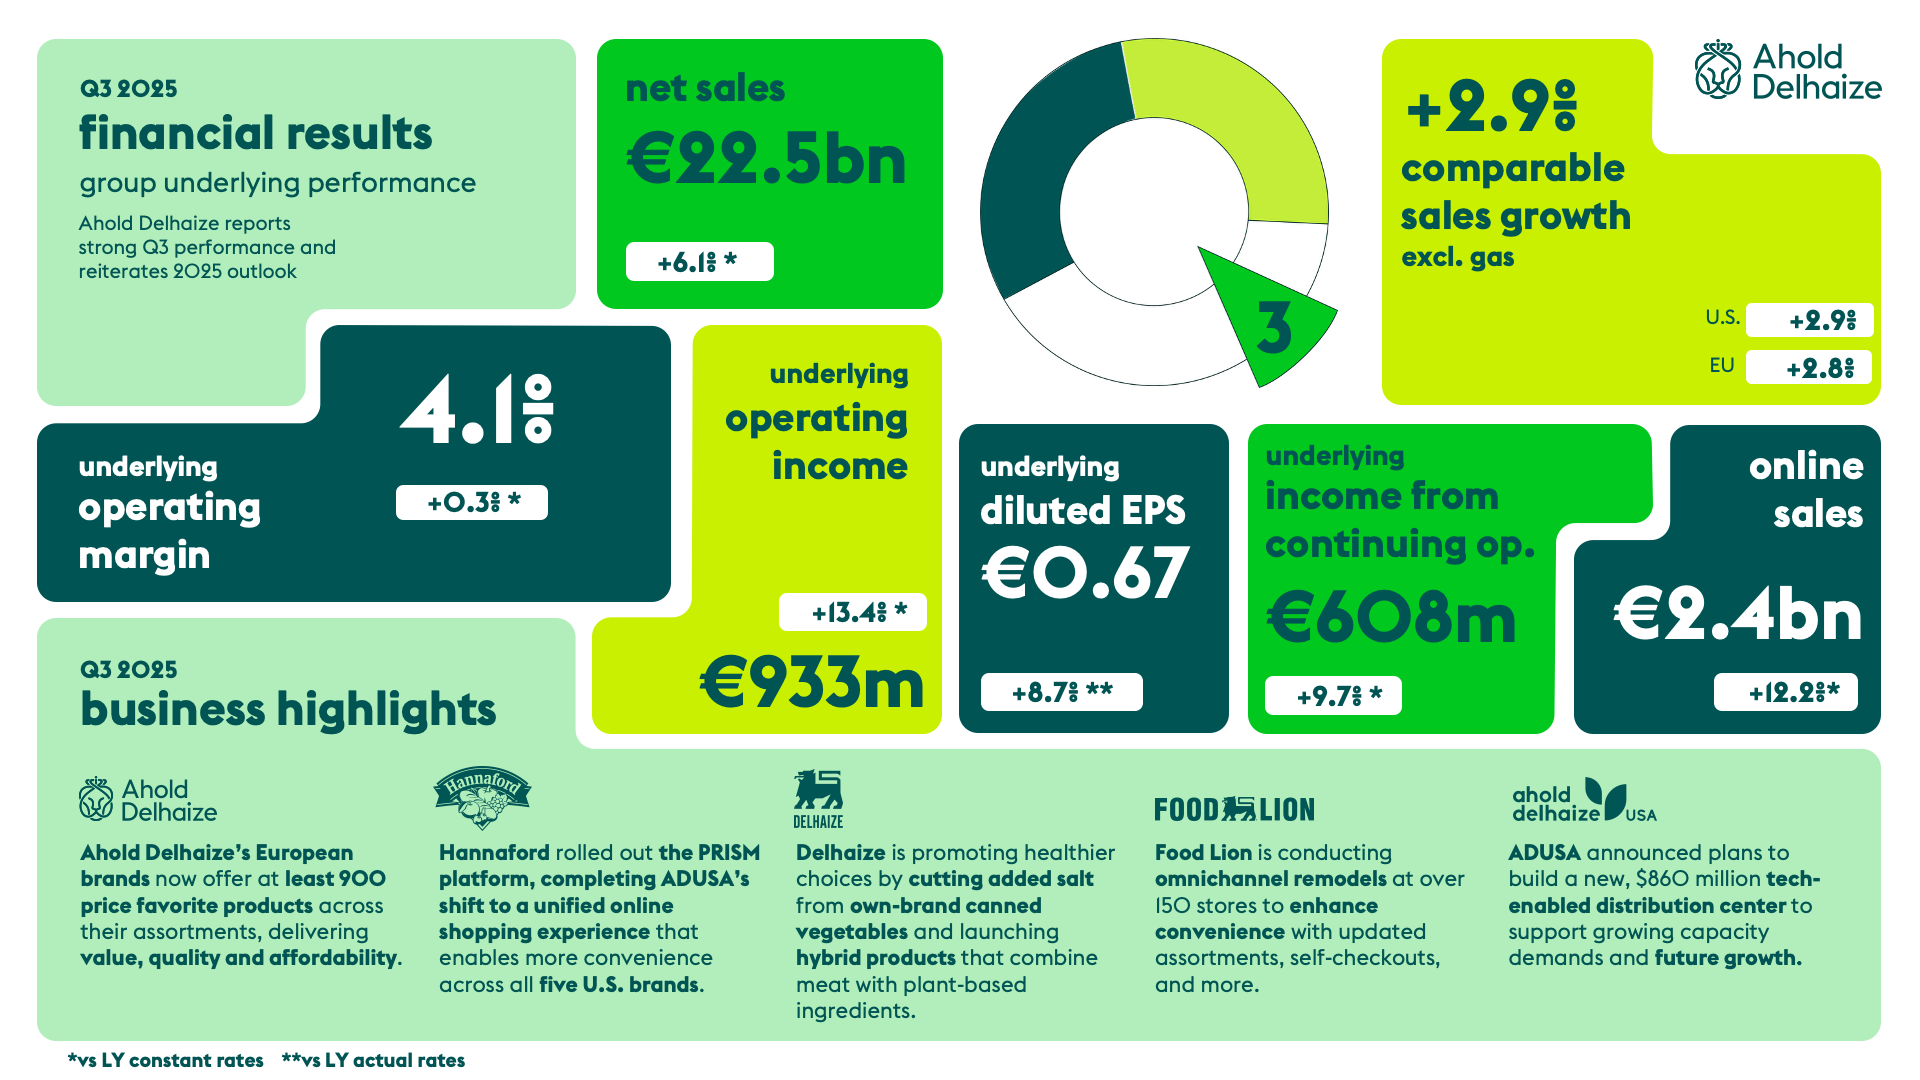
- Q3 net sales were €22.5 billion, up 6.1% at constant exchange rates and up 2.2% at actual exchange rates. Net sales were positively impacted by 3.6 percentage points at constant exchange rates from the acquisition of Profi and negatively impacted by 0.7 percentage points from the closure of Stop & Shop stores in the prior year and the cessation of tobacco sales in Belgium.
- Q3 comparable sales excluding gasoline increased by 2.9%, up 2.9% in the U.S. and 2.8% in Europe. Comparable sales excluding gasoline were negatively impacted by 0.2 percentage points in the U.S. due to weather. The cessation of tobacco sales led to a negative impact of 0.6 percentage points in Europe.
- Our brands' customers appreciate the convenience, assortments and personalization offered by our omnichannel shopping experiences, including the addition of new AI features. Ahold Delhaize's online sales increased by 12.2% in Q3 at constant exchange rates and 9.1% at actual exchange rates. This was driven by double-digit growth in online grocery in both regions and a strong performance at bol.
- Q3 underlying operating margin was 4.1%, an increase of 0.3 percentage points at constant exchange rates. Strong performance in the U.S., which included 0.2 percentage points benefit from non-recurring items, more than offset the impact of the first-time consolidation of Profi and strategic U.S. price investments to accelerate growth.
- Q3 IFRS operating income was €902 million and IFRS-diluted earnings per share (EPS) was €0.65. IFRS operating income was €31 million lower than underlying operating income.
- Q3 diluted underlying EPS was €0.67, an increase of 8.7% compared to the prior year at actual exchange rates.
- The Company reiterates its 2025 full-year outlook for underlying operating margin of around 4%; free cash flow of at least €2.2 billion; and gross capital expenditures of around €2.7 billion. Diluted underlying EPS is expected to grow at a mid- to high-single-digit rate, based on an average euro/U.S. dollar exchange rate for the full year of 1.10. Diluted underlying EPS results at actual exchange rates are subject to dollar volatility.
- Ahold Delhaize announces a €1 billion share buyback program to start at the beginning of 2026.
Zaandam, the Netherlands, November 5, 2025 – Ahold Delhaize, an international food retail group and a leader in both supermarkets and e-commerce, reports third quarter results today.
Summary of key financial data
1. Comparable sales growth excluding gasoline, net consumer online sales, underlying operating income and related margin, diluted underlying EPS, free cash flow, and the percentage changes at constant rates are alternative performance measures that are used throughout this report. For a description of alternative performance measures and a reconciliation between percentage changes and percentage changes at constant rates, see Note 13 in the full Interim Report.
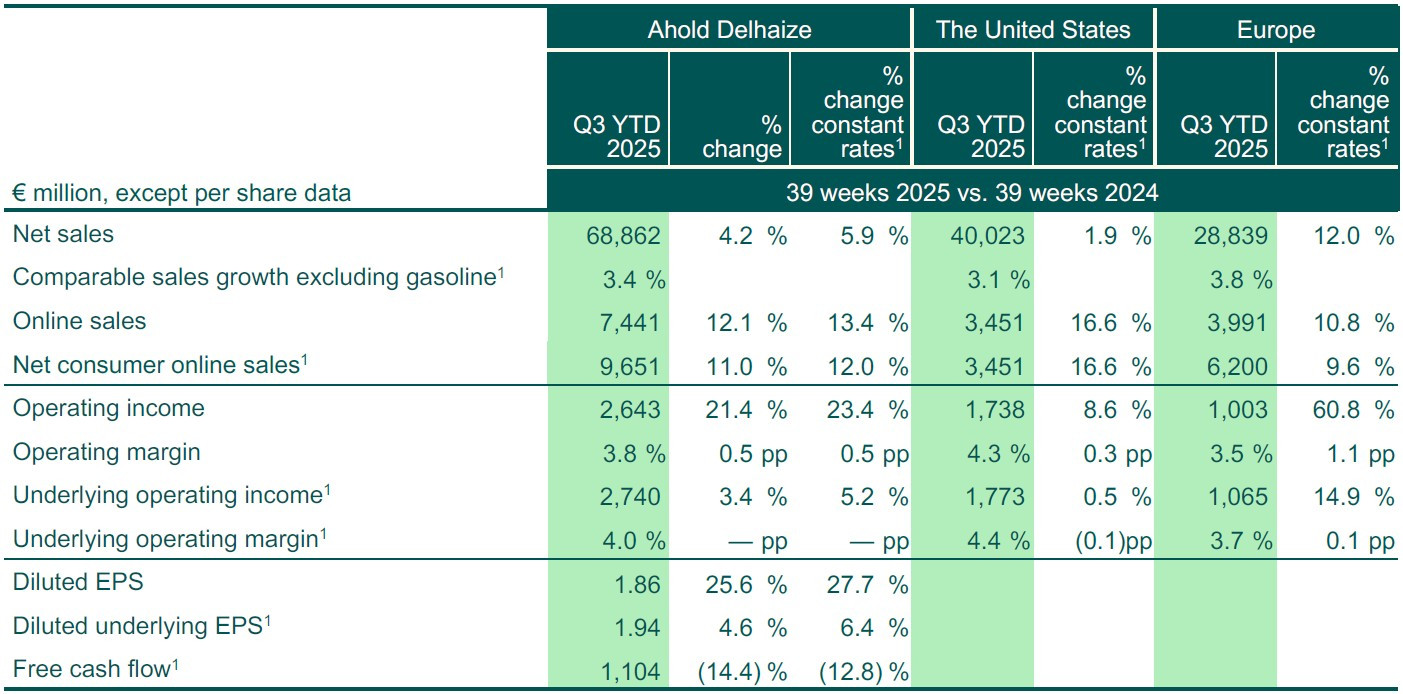
1. Comparable sales growth excluding gasoline, net consumer online sales, underlying operating income and related margin, diluted underlying EPS, free cash flow, and the percentage changes at constant rates are alternative performance measures that are used throughout this report. For a description of alternative performance measures and a reconciliation between percentage changes and percentage changes at constant rates, see Note 13 in the full Interim Report.
Comments from Frans Muller, President and CEO of Ahold Delhaize
“The capabilities we have cultivated within our organization provide us with the expertise and resilience to succeed in complex and dynamic environments. They enable us to scale successful solutions across our brands to unlock additional operational efficiencies. Thanks to the dedication and focus of our teams, we are making meaningful strides in advancing our Growing Together strategy. Our brands are creating value every day for customers by lowering prices, elevating our own-brand assortments, and collaborating with vendors to deliver impactful promotions. We are also sharpening our portfolio through remodels and enriching our omnichannel experiences to drive convenience and reach. This is all underpinned by the diligent execution of our Save for Our Customers program, which creates the fuel to maintain a steady pace of investment.
“Our third quarter results reflect the strong foundation and flexibility of our operating model. Net sales increased 6.1% at constant exchange rates (2.2% at actual exchange rates) and comparable sales growth excluding gasoline was 2.9%. Net sales were positively impacted by 3.6 percentage points from the Profi acquisition and negatively impacted by 0.7 percentage points from the closure of Stop & Shop stores and the cessation of tobacco sales in Belgium. We delivered a healthy and slightly higher-than-planned underlying operating margin of 4.1% despite dynamic conditions in several markets. As a result, diluted underlying EPS was up 8.7% at actual exchange rates.
“In the U.S., net sales increased 1.9% at constant exchange rates (decreased 4.3% at actual exchange rates), while comparable sales growth excluding gasoline increased 2.9%. The latter was negatively impacted by 0.2 percentage points from cycling the impact of hurricanes in the prior year. Two notable accomplishments were Food Lion's impressive 52nd consecutive quarter of comparable store sales growth and the completion of the roll-out of PRISM at Food Lion and Hannaford. With that, all the U.S. brands are now on the proprietary platform, which will allow us to increase the speed and impact of innovation in omnichannel convenience for customers moving forward. The Stop & Shop team has been laser focused over the past year on executing their pricing strategy, extending key elements and refinements to an additional 88 stores in Massachusetts during the quarter. At the same time, our associates are improving the quality of service and in-store execution, optimizing promotional effectiveness, and tightening day-today operations. While there is plenty of hard work ahead, I am encouraged by the positive response from customers.
“In Europe, net sales increased 12.4% at constant exchange rates (12.5% at actual exchange rates), including the impact of Profi. Comparable sales excluding gasoline increased 2.8%, negatively impacted by 0.6 percentage points from the cessation of tobacco sales. With rising inflation, stagnating economic growth and governmental policy moves, the business and customer climate is pressured. For example, in Serbia, the industry is facing severe headwinds to the operating model resulting from a government decree on the limitation of prices, while, in Romania, higher VAT rates and changes to the phasing of governmental food stamps to low-income consumers is negatively impacting customer spending power. Nevertheless, our brands continue to push the boundaries to navigate these dynamics and are working hard to sustain and grow their competitive positions. In particular, for customers, we are maintaining the high focus on value, leaning into strengthening affordable healthy and convenient assortments. All our European brands now have a minimum of 900 Price Favorite products across their assortments and continue to update and expand their fresh produce sections, focusing on the increased demand for convenience, healthy and ready-made meals.
“Looking towards the future, we are staying focused on our plans to enable new innovation and growth. With rapid developments in AI, we see many opportunities to accelerate across every domain of our business. We are making progress on building the foundational AI platforms that will enable us to scale winning AI solutions quickly and efficiently in the future. One solution we are already seeing success with is Albert Heijn's personal assistant "Steijn." Integrated into the brand's customer app, Steijn is accessible to millions of users to help answer the number one question in every household: “What's for dinner?” In addition, we are embedding AI more and more into our core business processes, such as dynamic pricing, vendor negotiations and store operations, to drive productivity and simplify daily tasks.
“Our U.S. brands are solidifying their real estate pipelines to accelerate new store openings in the coming years. In North Carolina, Food Lion launched omnichannel remodels at 153 stores in its Charlotte market and has started construction on 92 store remodels in the Greensboro market. We also recently announced plans for Ahold Delhaize USA to build a new distribution center in North Carolina to meet growing capacity demands. This state-of-the-art facility will leverage the learnings and technology we employ at our automated facility in the Netherlands. We will also scale the proprietary retail media platform, Edge, from our European brands to our U.S. brands in the coming year.
“In Europe, we will bring new energy to increasing customer reach as we move into the new year. Delhaize Belgium is expanding its footprint with eight new supermarkets that will open in early 2026 under the brand's affiliate model. We also continue to make good progress on the integration of Profi, where we see a strong future growth path. Over the past three years, the brand has opened over 200 stores and intends to ramp up expansion plans in the next three years.
“Alongside our financial results, we continue making progress on our ambitions around healthy communities & planet. Our efforts continue to reinforce our strong existing ESG ratings, including our MSCI AA and Sustainalytics Low Risk ratings, which have been recently re-confirmed. One initiative I am excited about is the launch of our Healthy Future Academy. This new learning program equips associates with the knowledge, skills and confidence to further integrate health and sustainability into their daily work. The program takes learners on a journey from farm to plate, covering topics like nature and climate, circularity, and health, throughout Ahold Delhaize’s value chain.
“We are also taking steps in our ambition to make healthier and sustainable products affordable and accessible to all. For example, Delhaize Belgium has reformulated own-brand canned vegetables to eliminate added salt. And the brand has launched a new range of hybrid products that combine the familiar taste of meat with the benefits of plant-based ingredients. In addition, we continue to foster collaboration with suppliers across our value chain to support regenerative farming and reduce greenhouse gas (GHG) emissions. Most recently, Ahold Delhaize USA introduced a partnership with Danone North America and The Nature Conservancy that aims to enhance farm and supply chain resilience and reduce methane from yogurt production over the next five years. This follows earlier partnerships with Kellanova, General Mills and Campbell's Soup.
“As 2025 draws to a close, I am proud of our progress and, more importantly, that we have sustained and strengthened brand equity and leading market positions across the portfolio. Over the next months, our priority is to deliver a strong holiday experience for our customers, prioritizing value, healthy assortments, convenience and everything they need to create their own special and unique holiday moments. At the same time, we will stay agile and take measures to reinforce our strategic levers and refine our operations appropriately to ensure we are well prepared to carry momentum into the new year.
“Given our solid performance year-to-date and our continued financial discipline, we have the resilience, flexibility and culture to adapt to the opportunities and risks ahead. I am confident we are taking the right measures to drive consistent growth and long-term value creation. Underscoring this, I am pleased to announce the continuation of our annual share buyback program in 2026 for €1 billion, and reiterate our promises for the Growing Together strategic planning period.”
Q3 Financial highlights
Group highlights
Ahold Delhaize net sales were €22.5 billion, an increase of 6.1% at constant exchange rates and up 2.2% at actual exchange rates. Our net sales growth was driven by the Profi acquisition, comparable sales growth excluding gasoline of 2.9% and store openings, partially offset by the closure of Stop & Shop stores and lower gasoline sales. The Company's Q3 comparable sales excluding gasoline were negatively impacted by 0.1 percentage points due to weather, and by 0.3 percentage points from the cessation of tobacco sales at supermarkets in Belgium.
In Q3, Ahold Delhaize's online sales increased 12.2% at constant exchange rates. This was driven by double-digit growth in online grocery in both regions and a strong performance at bol.
Ahold Delhaize underlying operating margin was 4.1%, an increase of 0.3 percentage points at constant rates. Strong performance in the U.S., supported by non-recurring items that added 0.2 percentage points to its margin, more than offset the impact of the first-time consolidation of Profi and price investments in the U.S.
In Q3, Ahold Delhaize IFRS operating income was €902 million, representing an IFRS operating margin of 4.0%.
Diluted EPS was €0.65 and diluted underlying EPS was €0.67, up 8.7% at actual exchange rates compared to last year's results.
In the quarter, Ahold Delhaize purchased 10.5 million of its own shares for €371 million, bringing the total amount to €813 million in the first three quarters of the year.
U.S. highlights
U.S. net sales were €12.9 billion, an increase of 1.9% at constant exchange rates and down 4.3% at actual exchange rates. Comparable sales excluding gasoline in the U.S. increased 2.9%, driven by continued growth in online and pharmacy sales. Weather had a negative impact of approximately 0.2 percentage points. Net sales were negatively impacted by 0.8 percentage points from the closure of Stop & Shop stores and lower gasoline sales.
In Q3, online sales increased 15.4% at constant exchange rates, led by strong growth at Food Lion.
Underlying operating margin in the U.S. was 4.6%, up 0.4 percentage points. Higher sales leverage, a shift in the timing of promotional activities, and one time non-recurring items more than offset price investments and dilutive impact from growth in online and pharmacy sales.
U.S. IFRS operating income was €590 million, representing an IFRS operating margin of 4.6%. IFRS results were €2 million lower than underlying results.
Europe highlights
European net sales were €9.6 billion, an increase of 12.4% at constant exchange rates and 12.5% at actual exchange rates. The higher net sales were partly due to the Profi acquisition, an increase in comparable sales of 2.8% and store openings. Europe's comparable sales excluding gasoline had a negative impact of 0.6 percentage points resulting from the cessation of tobacco sales at supermarkets in Belgium.
In Q3, online sales increased 9.7%, driven by double-digit growth at Albert Heijn and strong performance at bol.
Underlying operating margin in Europe was 3.9%, in line with the prior year. Improvements in Belgium and improved labor productivity were offset by the impact of the first-time consolidation of Profi and lower profitability levels in Serbia due to new governmental decree on grocery industry pricing. Europe's Q3 IFRS operating income was €346 million, representing an IFRS operating margin of 3.6%.
Outlook
Following the first nine months of the year, Ahold Delhaize reiterates its 2025 outlook. Underlying operating margin is expected to be around 4%; free cash flow is expected to be at least €2.2 billion; and gross capital expenditures are planned at around €2.7 billion. Diluted underlying EPS is expected to grow at a mid- to high-single-digit rate, based on an average euro/U.S. dollar exchange rate for the full year of 1.10. Diluted underlying EPS results at actual exchange rates are subject to dollar volatility.
The following are changes in the business that will impact comparable performance for 2025 and that have been incorporated into our Outlook:
- The acquisition of Profi closed on January 3, 2025, and is expected to add over €2.8 billion in net sales. This is slightly lower than our original expectation due to the impact of the phasing of governmental support benefits, the progress on store openings and closures and foreign exchange rate movements.
- The closure of underperforming Stop & Shop stores was completed in 2024. The estimated net impact to 2025 reported net sales from these closures is expected to be between $400 and $425 million.
- The cessation of tobacco sales impacted Albert Heijn's net sales at franchised stores for the first half of the year. In addition, Delhaize and Albert Heijn stores in Belgium ended tobacco sales as of April 1, 2025, due to regulation changes. This will have around a 1.0 percentage-point impact on reported and comparable store sales in Europe in 2025.
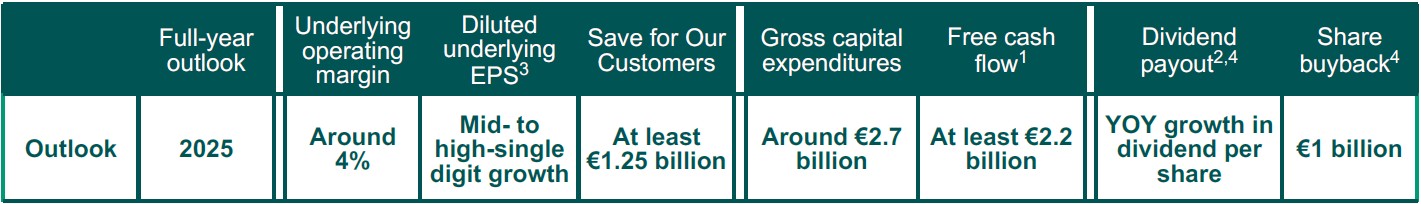
1. Excludes M&A.
2. Calculated as a percentage of underlying income from continuing operations.
3. Based on an average euro/U.S. dollar exchange rate for the full year of 1.10.
4. Management remains committed to the company's share buyback and dividend programs while continuously assessing macroeconomic, geopolitical, and legislative factors as part of its decision-making process. In addition, the programs may be adjusted in response to corporate activities, including significant mergers and acquisitions.
downloads
webcast
This communication contains information that qualifies as inside information within the meaning of Article 7(1) of the EU Market Abuse Regulation.
This communication includes forward-looking statements. All statements other than statements of historical facts may be forwardlooking statements. Forward-looking statements can be identified by certain words, such as “anticipate,” “intend,” “plan,” “goal,” “seek,” “believe,” “project,” “estimate,” “expect,” “strategy,” “future,” “likely,” “may,” “should,” “will” and similar references to future periods.
Forward-looking statements are subject to risks, uncertainties and other factors that are difficult to predict and that may cause the actual results of Koninklijke Ahold Delhaize N.V. (the “Company”) to differ materially from future results expressed or implied by such forward-looking statements. Therefore, you should not place undue reliance on any of these forward-looking statements. Factors that might cause or contribute to such a material difference include, but are not limited to, risks relating to the Company’s inability to successfully implement its strategy, manage the growth of its business or realize the anticipated benefits of acquisitions; risks relating to competition and pressure on profit margins in the food retail industry; the impact of economic conditions, including high levels of inflation, on consumer spending; changes in consumer expectations and preferences; turbulence in the global capital markets; political developments, natural disasters and pandemics; wars and geopolitical conflicts; climate change; energy supply issues; raw material scarcity and human rights developments in the supply chain; disruption of operations and other factors negatively affecting the Company’s suppliers; the unsuccessful operation of the Company’s franchised and affiliated stores; changes in supplier terms and the inability to pass on cost increases to prices; risks related to environmental, social and governance matters (including performance) and sustainable retailing;risks related to data management and data privacy; food safety issues resulting in product liability claims and adverse publicity; environmental liabilities associated with the properties that the Company owns or leases; competitive labor markets, changes in labor conditions and labor disruptions; increases in costs associated with the Company’s defined benefit pension plans; ransomware and other cybersecurity issues relating to the failure or breach of security of IT systems; the Company’s inability to successfully complete divestitures and the effect of contingent liabilities arising from completed divestitures; antitrust and similar legislation; unexpected outcomes in the Company’s legal proceedings; additional expenses or capital expenditures associated with compliance with federal, regional, state and local laws and regulations; unexpected outcomes with respect to tax audits; the impact of the Company’s outstanding financial debt; the Company’s ability to generate positive cash flows; fluctuation in interest rates; the change in reference interest rate; the impact of downgrades of the Company’s credit ratings and the associated increase in the Company’s cost of borrowing; exchange rate fluctuations; inherent limitations in the Company’s control systems; changes in accounting standards; inability to obtain effective levels of insurance coverage; adverse results arising from the Company’s claims against its self-insurance program; the Company’s inability to locate appropriate real estate or enter into real estate leases on commercially acceptable terms; and other factors discussed in the Company’s public filings and other disclosures.
Forward-looking statements reflect the current views of the Company’s management and assumptions based on information currently available to the Company’s management. Forward-looking statements speak only as of the date they are made, and the Company does not assume any obligation to update such statements, except as required by law.